Volvo Cars will roll out 13 new models by 2030, split between seven Western-market vehicles and six developed with Geely for China, as it targets an EBIT margin above 8% from 3.5% in 2025.
Volvo Cars will roll out 13 new models by 2030, split between seven Western-market vehicles and six developed with Geely for China, as it targets an EBIT margin above 8% from 3.5% in 2025.
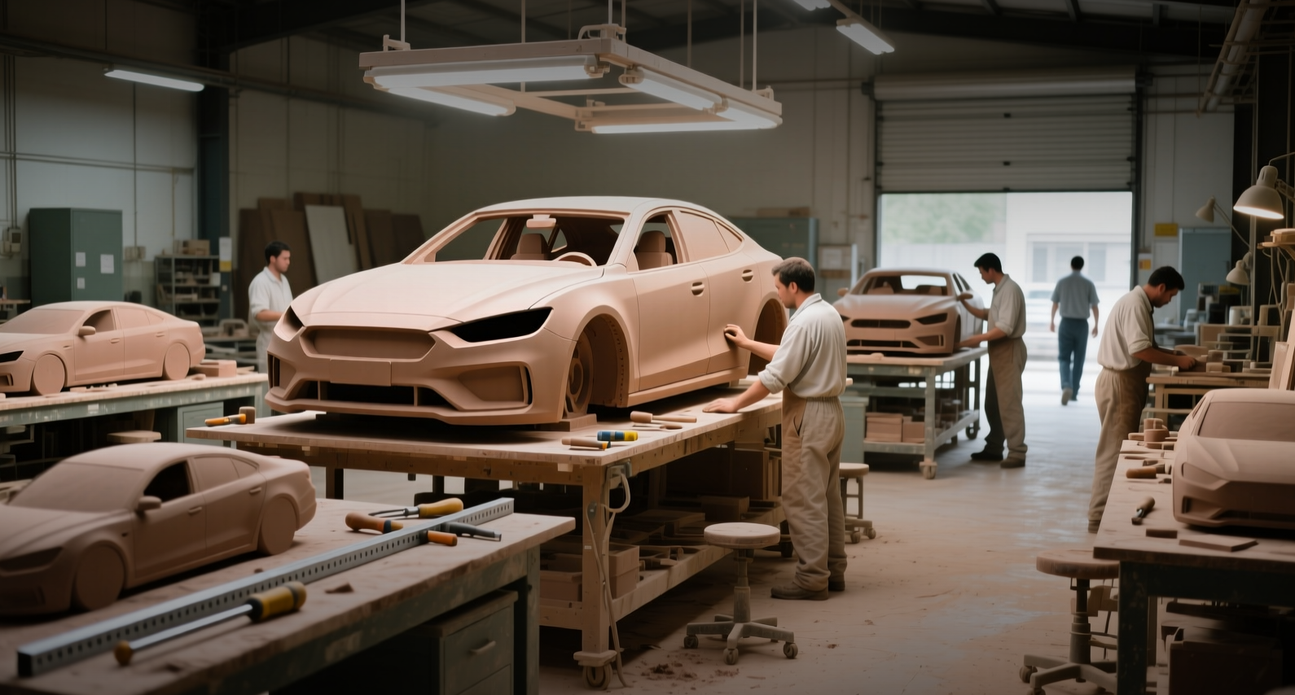
Seven new vehicles for Western buyers, six more built with Geely for China, and a margin target that has eluded Volvo Cars for years. That is the shape of the Swedish automaker's biggest product push to date, laid out ahead of an investor day in Stockholm on Thursday.
"Our product offensive builds on four unique strengths: regionalised product offerings, leadership in electrification, unique synergies with Geely, and complete customer offers that goes beyond the car alone," CEO Hakan Samuelsson said in a statement.
The 13 launches are split by architecture as much as by geography. The seven Western-market vehicles will ride on Volvo's own SPA2 and SPA3 platforms, the family that underpins its current electric range. The six China-focused models will be developed jointly with Geely Auto, the Zhejiang-based group that has controlled Volvo since 2010. Under Samuelsson, Volvo has cut customisation and pushed decision-making closer to each region, a reversal of the global-platform orthodoxy that once defined the industry.
The margin math is the hard part. Volvo's 3.5% EBIT margin in 2025 sits well below the 8% target it has chased for years, and below the double-digit margins BMW and Mercedes-Benz routinely report. Closing that gap requires the new models to sell at higher prices without a matching rise in development spending — a difficult trade when a single new platform can cost $1 billion or more to engineer.
That is where the Geely arrangement earns its keep. By co-developing the six China models with its parent, Volvo spreads engineering and tooling costs across a larger volume base, and gains access to Geely's local supply chain and battery sourcing. Geely Auto sold more than 2 million vehicles in 2025, giving the shared architecture a scale Volvo alone could not reach. The trade-off is differentiation: models built on shared Geely underpinnings risk competing on price rather than brand in the world's most crowded EV market.
The Western lineup faces a different problem. Europe's EV demand has cooled from its 2023 peak as subsidy programs wound down and charging buildout lagged, pushing buyers toward hybrids. Volvo's answer has been to keep combustion and plug-in hybrid options alongside battery-electric cars rather than betting the lineup on one powertrain — a hedge that costs capital but protects volume. The 2028 XC60 and XC90 plug-in hybrids, reported as filling the gap between hybrid and electric, sit squarely in that strategy.
Competitive pressure is intensifying on both fronts. In China, BYD, Chery and SAIC's MG have pushed into Europe with hybrid-heavy lineups — MG's Hybrid+ family sold 137,000 units in Europe in 2025, up 300% year on year, against roughly 46,000 battery-electric cars. In the premium segment, BMW and Mercedes-Benz continue to refresh their electric ranges on fixed cycles. Volvo's 13 launches must land on schedule to avoid ceding showroom space in either region.
The capex implication is the number investors should watch. A 13-model program spread across two platform families and two development organisations implies elevated research and development spending through the decade, with the payoff back-loaded toward 2028-2030. Volvo has not disclosed the total investment figure for the program, nor a model-by-model launch calendar.
For shareholders, the roadmap is a medium-term story rather than an immediate earnings trigger. Volvo Cars is listed in Stockholm and majority-owned by Geely, and its shares have traded well below the levels seen before its 2021 listing as margin recovery stalled. The 8% EBIT target is the single metric that will determine whether the product offensive is judged a success — and the company has not set a firm date for reaching it. The next hard checkpoint is the investor day itself, where management is expected to detail the launch sequence and the spending behind it.
This article is for informational purposes only and does not constitute investment advice.