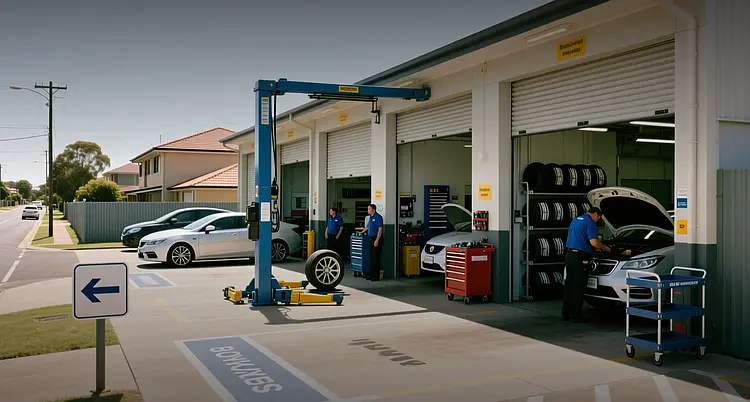
Tuhu Car agreed to acquire Continental's Australian tyre and repair chain mycar Tyre & Auto for an enterprise value of A$403 million, a deal that hands the Chinese platform 279 stores and its first scaled operating footprint outside mainland China.
The Shanghai-based company will buy the entire issued share capital of Conti Trade Australia Pty Ltd from a wholly owned subsidiary of Continental AG, according to a Hong Kong exchange filing. The estimated completion payment is A$278.33 million, roughly HKD1.55 billion, and remains subject to adjustment for the target's net debt and working capital.
"The acquisition provides a strategic opportunity to establish scaled direct business operations in the Australian automotive service market," Tuhu said in the filing, adding that it would diversify geographic distribution and expand its international footprint.
The A$403 million headline figure is not the final cash outlay. Completion payments of this type are struck on a locked-box or completion-accounts basis, and a post-completion calculation can move the total materially in either direction. Tuhu has not disclosed the multiple it is paying on mycar's earnings, and no premium to an undisturbed price applies because Conti Trade Australia is not separately listed.
Two approvals that cannot be waived
Completion rests on two conditions Tuhu cannot walk away from. The first is an outcome from the Australian Competition and Consumer Commission, which will assess whether the transfer of 279 company-owned service outlets to a single foreign buyer concentrates the retail tyre and repair market. The second is foreign investment approval, required because the acquirer is a Chinese state-adjacent platform taking control of an Australian consumer services network.
Neither condition carries a waiver right. If either fails, the transaction does not close. Tuhu did not disclose a long-stop date or a break fee in the filing, and the company has not named financial advisers on either side of the transaction.
The regulatory bar is the single largest source of execution risk in the deal. Australia's foreign investment review framework has tightened for Chinese acquirers in consumer-facing sectors since 2020, and the ACCC has previously required divestitures in retail service roll-ups where local market share crossed thresholds. Tuhu's filing gives no indication of mycar's share of the Australian tyre retail market, which is the metric the ACCC will test first.
Funding is approved, but the leverage is new
Tuhu has obtained credit approval from lending banks for acquisition financing of no more than RMB1 billion, equivalent to about A$213 million at prevailing rates. The company said it will fund the settlement payment through a combination of that debt and its own internal cash resources.
The facility covers roughly three-quarters of the estimated A$278.33 million completion payment, leaving the balance to be met from Tuhu's balance sheet. Tuhu has not disclosed the interest rate, tenor, or covenant package attached to the credit approval, nor whether the facility is secured against the Australian assets or guaranteed at the parent level.
For a company whose revenue base is almost entirely China-derived, the addition of RMB1 billion in acquisition debt introduces both leverage and currency mismatch. The debt is denominated in renminbi while the acquired cash flows are in Australian dollars, leaving the servicing cost exposed to moves in the AUD/CNY cross.
What 279 stores actually buy
The strategic logic is speed. Building 279 service bays organically in a mature market with established incumbents would take years and cost more than the purchase price in cumulative lease, fit-out, and customer-acquisition spending. Buying an operating chain converts that timeline into a single closing.
The network gives Tuhu a direct retail presence in a market where vehicle ownership per capita is high and average vehicle age has been rising, both of which support tyre replacement and maintenance volumes. It also puts Tuhu into competition with established Australian operators and with the local franchise networks of global tyre makers, a set of rivals it has never faced.
Continental, for its part, exits a non-core consumer services business. The German group has been narrowing its portfolio toward tyre manufacturing and automotive technology, and mycar's retail service economics sit outside that focus.
Tuhu's Hong Kong-listed shares rose 5.068% to trade at HK$10.78, with short-selling turnover of $2.40 million representing 31.088% of turnover as of 2026-09-23 16:25, according to AASTOCKS data. The elevated short ratio shows a meaningful cohort of traders treating the deal's regulatory path as the variable that decides whether the premium holds.
The next hard data point is the ACCC's review timetable, which Tuhu has not yet disclosed. Until both approvals land, the A$278.33 million payment stays contingent and the 279 stores stay with Continental.
This article is for informational purposes only and does not constitute investment advice.