Robotechnik, a supplier of photovoltaic manufacturing equipment and systems, began taking orders for its Hong Kong initial public offering on Monday, offering 11.876 million H shares at a maximum of HK$436 apiece to raise as much as HK$5.178 billion ($663 million).
The Shenzhen-based company has lined up 16 cornerstone investors, including Singapore state fund Temasek, E Fund, CIG, Winner Global Fund, Wind Sabre, Arrowpoint, Sino Opulence Fund and Bloom Capital, according to the listing document. The group has committed to subscribe for shares worth about $232 million, roughly 35% of the maximum deal size.
The Hong Kong public offering accounts for about 10% of the shares on sale, with the international placing taking the remaining 90%. A board lot of 50 shares puts the minimum entry cost at HK$22,019.85, a level that restricts the retail tranche to higher-ticket buyers. Net proceeds are estimated at about HK$4.961 billion based on the top-end price.
The bookbuild runs from Monday to Thursday, with pricing expected on July 24 and a Main Board debut scheduled for July 29. The company did not disclose the lead underwriters, a greenshoe option or a lockup period for the cornerstone investors in the announcement.
Temasek's participation places the deal alongside a run of Hong Kong listings that have leaned on sovereign and strategic money to clear large floats. The presence of a long-duration anchor of that scale typically narrows the free float available to public buyers and can compress the price discovery window during the bookbuild.
The HK$436 ceiling values the offer at a premium to the entry point many retail investors use to gauge Hong Kong new listings, where a HK$22,019.85 minimum ticket sits well above the HK$5,000 to HK$10,000 range common on smaller Main Board deals. That structure points to an institutional-led allocation rather than a retail-driven oversubscription.
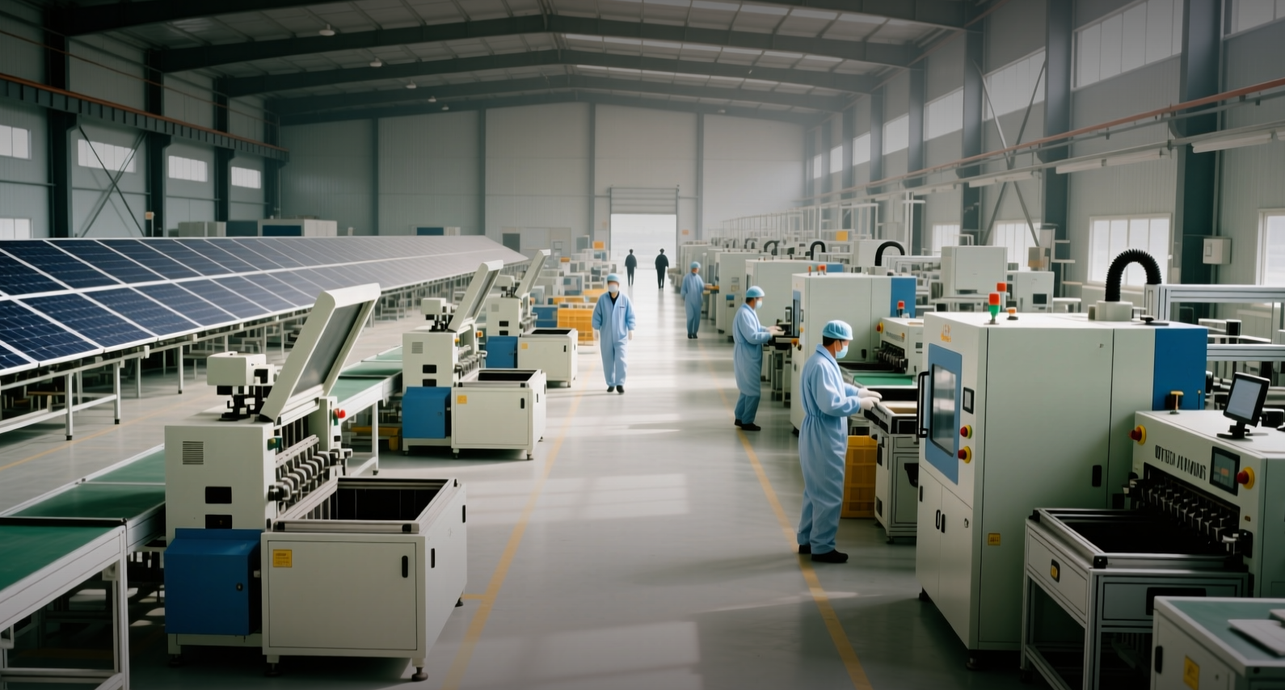
Robotechnik supplies equipment and systems to photovoltaic manufacturers, a segment tied to the capital spending cycles of solar cell and module producers. Demand for that equipment has tracked the pace of capacity additions across Chinese solar supply chains, which have swung sharply over the past two years as module prices fell and producers slowed expansion.
The cornerstone commitments give the deal a floor of committed demand before the institutional book opens, but they also concentrate the register. If the international tranche prices at the top of the range, the $232 million anchor block represents a substantial share of a float that is already thin at 11.876 million shares.
Investors will watch the July 24 pricing for the final offer price and any clawback of shares from the international placing to the Hong Kong tranche, which would indicate retail demand running ahead of the initial 10% allocation. First-day trading on July 29 will test whether the cornerstone-led structure holds at the HK$436 ceiling.
This article is for informational purposes only and does not constitute investment advice.