JPMorgan began coverage of KB Laminates (1888.HK) at Overweight with a HKD65 target price, arguing the world's largest conventional copper clad laminate maker will lift earnings eightfold between 2025 and 2028 as an electronic-grade glass fiber cloth shortage hands pricing power to integrated suppliers.
The broker's thesis rests on a supply squeeze it expects to outlast the current cycle. Prices for electronic-grade glass fiber cloth have climbed more than 100% since the start of 2026, driven by AI and general-purpose server demand, and JPMorgan expects the shortage to persist at least through 2027 with further increases likely. Morgan Stanley has separately said the same shortage should run through 2027.
Shares rose 6.6% to HKD49.20 on the initiation, with short selling of HKD843.35 million representing 22.8% of turnover.
The HKD65 target is built on 20x forecast 2027 earnings, in line with the average for the Asian PCB supply chain, and already embeds a 30% discount for investor concern over changes in the founding family's shareholding. That discount is the crux of the call: JPMorgan argues the overhang has passed. The founding family sold shares in parent KINGBOARD HLDG (148.HK) during June and July 2026, a stretch that coincided with a 72% decline in KB Laminates against a 12% gain in the Hang Seng Index. Further reduction below 30% — the family holds 31.8% — could trigger a mandatory general offer under HKEX rules if its investment vehicles seek to regain control. Exchange filings show the family and management resumed buying both KINGBOARD HLDG and KB Laminates after strong first-half 2026 results.
Looms, copper foil and a 150% ASP increase
The earnings forecast leans on volume and mix rather than price alone. JPMorgan models a cumulative 150% increase in blended CCL average selling prices through 2028, combining industry shortage pricing with a migration toward higher-grade product. General server shipments are forecast to grow 22% in 2026 and 25% in 2027, pulling demand for M4 through M7 grade CCL.
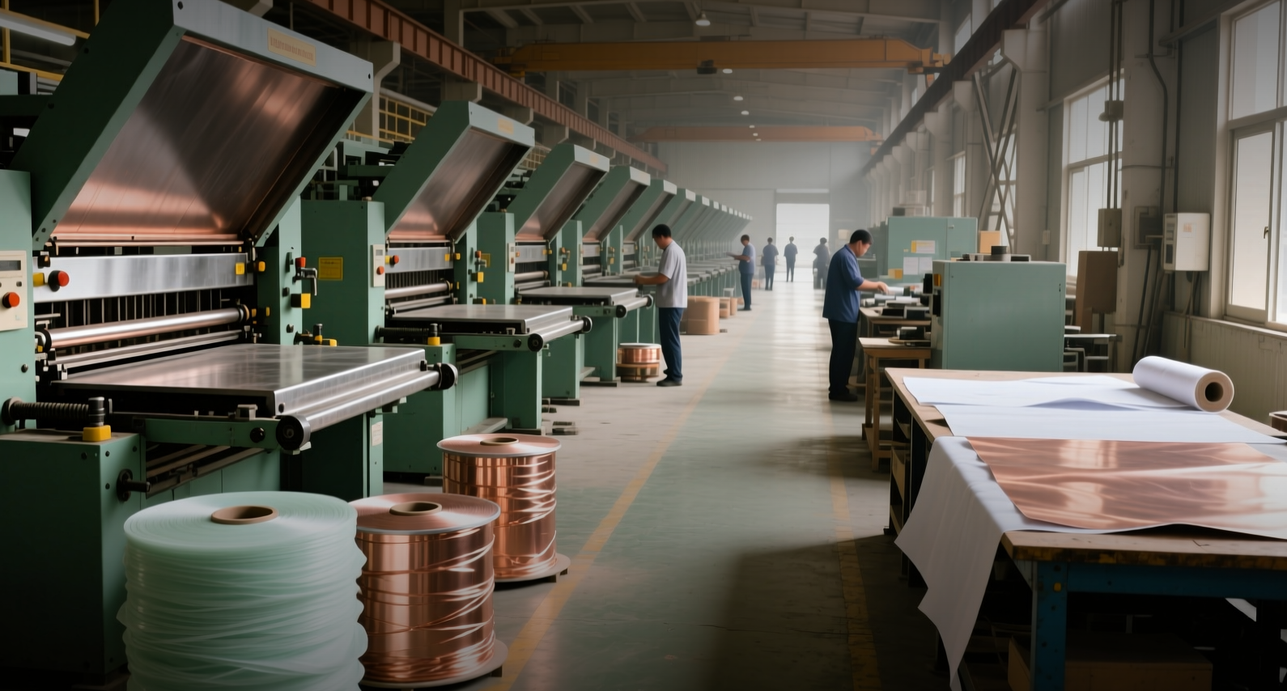
Capacity is the second lever. KB Laminates has secured roughly 35% to 40% of Toyota's loom allocation for the next two years, and its loom fleet is expected to expand from about 3,300 units in 2026 to roughly 5,800 units in 2028. That drives approximately 55% growth in glass fiber cloth output, including specialty products, between 2025 and 2028 and contributes more than HKD5 billion in net profit growth. The company is also expanding "T-cloth" capacity fivefold and has begun supplying core CCL customers including SYTECH (600183.SH).
In copper foil, KB Laminates runs about 63,000 tonnes of annual capacity. Output of HVLP1-3 product from the new Fogang plant, with 21,000 tonnes of annual capacity, is expected to ramp from the third quarter of 2027, with potential customer certification for HVLP4. JPMorgan expects copper foil processing fees to rise 20% to 60% in 2026.
The broker argues this upcycle can run longer than the 2015-2017 and 2019-2021 cycles because AI specification migration is accelerating while capacity conversions are generating losses elsewhere in the industry. KB Laminates is one of only two companies with a fully integrated PCB materials supply chain, alongside Taiwan's Nan Ya Plastics.
What the rating means for holders
At 15x forecast 2026 earnings and 10x for 2027, the stock trades above its 10-year average of 12.5x — a premium that only holds if the glass fiber cloth shortage persists and the loom expansion lands on schedule. The near-term test is the Fogang copper foil ramp in the third quarter of 2027 and whether HVLP4 certification follows; the nearer-term signal is whether the founding family's buying continues through the next set of exchange filings.
This article is for informational purposes only and does not constitute investment advice.