JPMorgan Chase began coverage of Dajin Heavy Industry Co. with an Overweight rating and a HK$43 price target, betting the Chinese offshore wind foundation maker's earnings rebound in 2027 as European order growth accelerates and currency and freight costs stop eating into margins.
Alan Hon, the JPMorgan analyst who initiated the rating on Sept. 22, wrote that the company is a leading global supplier of offshore wind foundations and that the stock's slide since mid-2026 has left the valuation attractive relative to a multi-year European buildout cycle.
The initiation is the first sell-side rating on the name from a U.S. bulge-bracket bank this cycle. Dajin Heavy, which trades in Hong Kong under the ticker 01081, has rebounded about 20% since Sept. 9 as investors revisited the shares. The company's earnings guidance was cut earlier in 2026 on foreign-exchange losses and logistics costs, and JPMorgan expects those drags to fade into 2027.
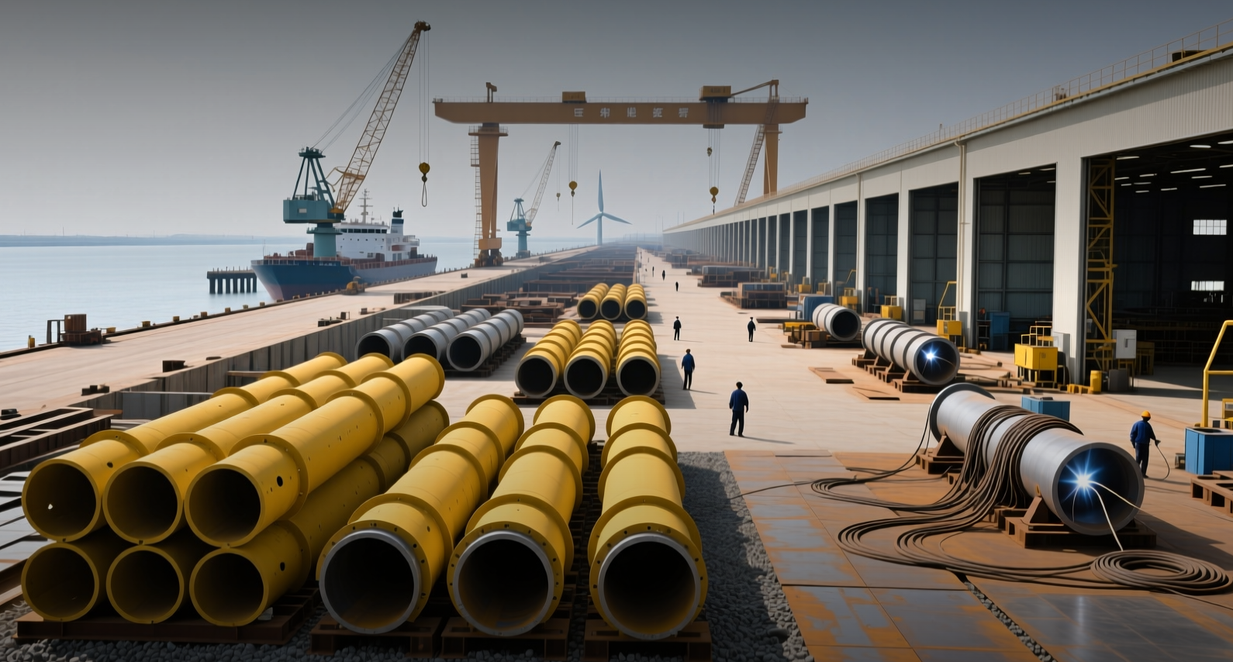
Two European developments drove the re-rating. Germany introduced a contracts-for-difference mechanism for offshore wind, giving developers a revenue floor that supports final investment decisions, and the Waterekke offshore project reached grid connection. Both events pull forward demand for monopiles and transition pieces, the steel foundations Dajin Heavy manufactures.
The read-across extends beyond one company. European offshore wind installation schedules feed a supply chain that includes wind turbine makers and foundation fabricators across China and Europe, and a sustained order recovery would lift utilization rates at yards that have run below capacity since 2024.
Dajin Heavy's Hong Kong listing gives global investors direct exposure to that buildout without holding A-share positions. The stock's move since Sept. 9 has outpaced the broader Hong Kong market, though the shares remain below their mid-2026 levels, when the earnings downgrade cycle began.
The key test comes with the company's next results and order intake disclosure, when investors will look for European contract wins to confirm that the German policy shift is converting into signed backlog rather than pipeline announcements. JPMorgan's HK$43 target implies further upside from current levels, but the thesis depends on the 2027 earnings recovery arriving on schedule.
This article is for informational purposes only and does not constitute investment advice.